

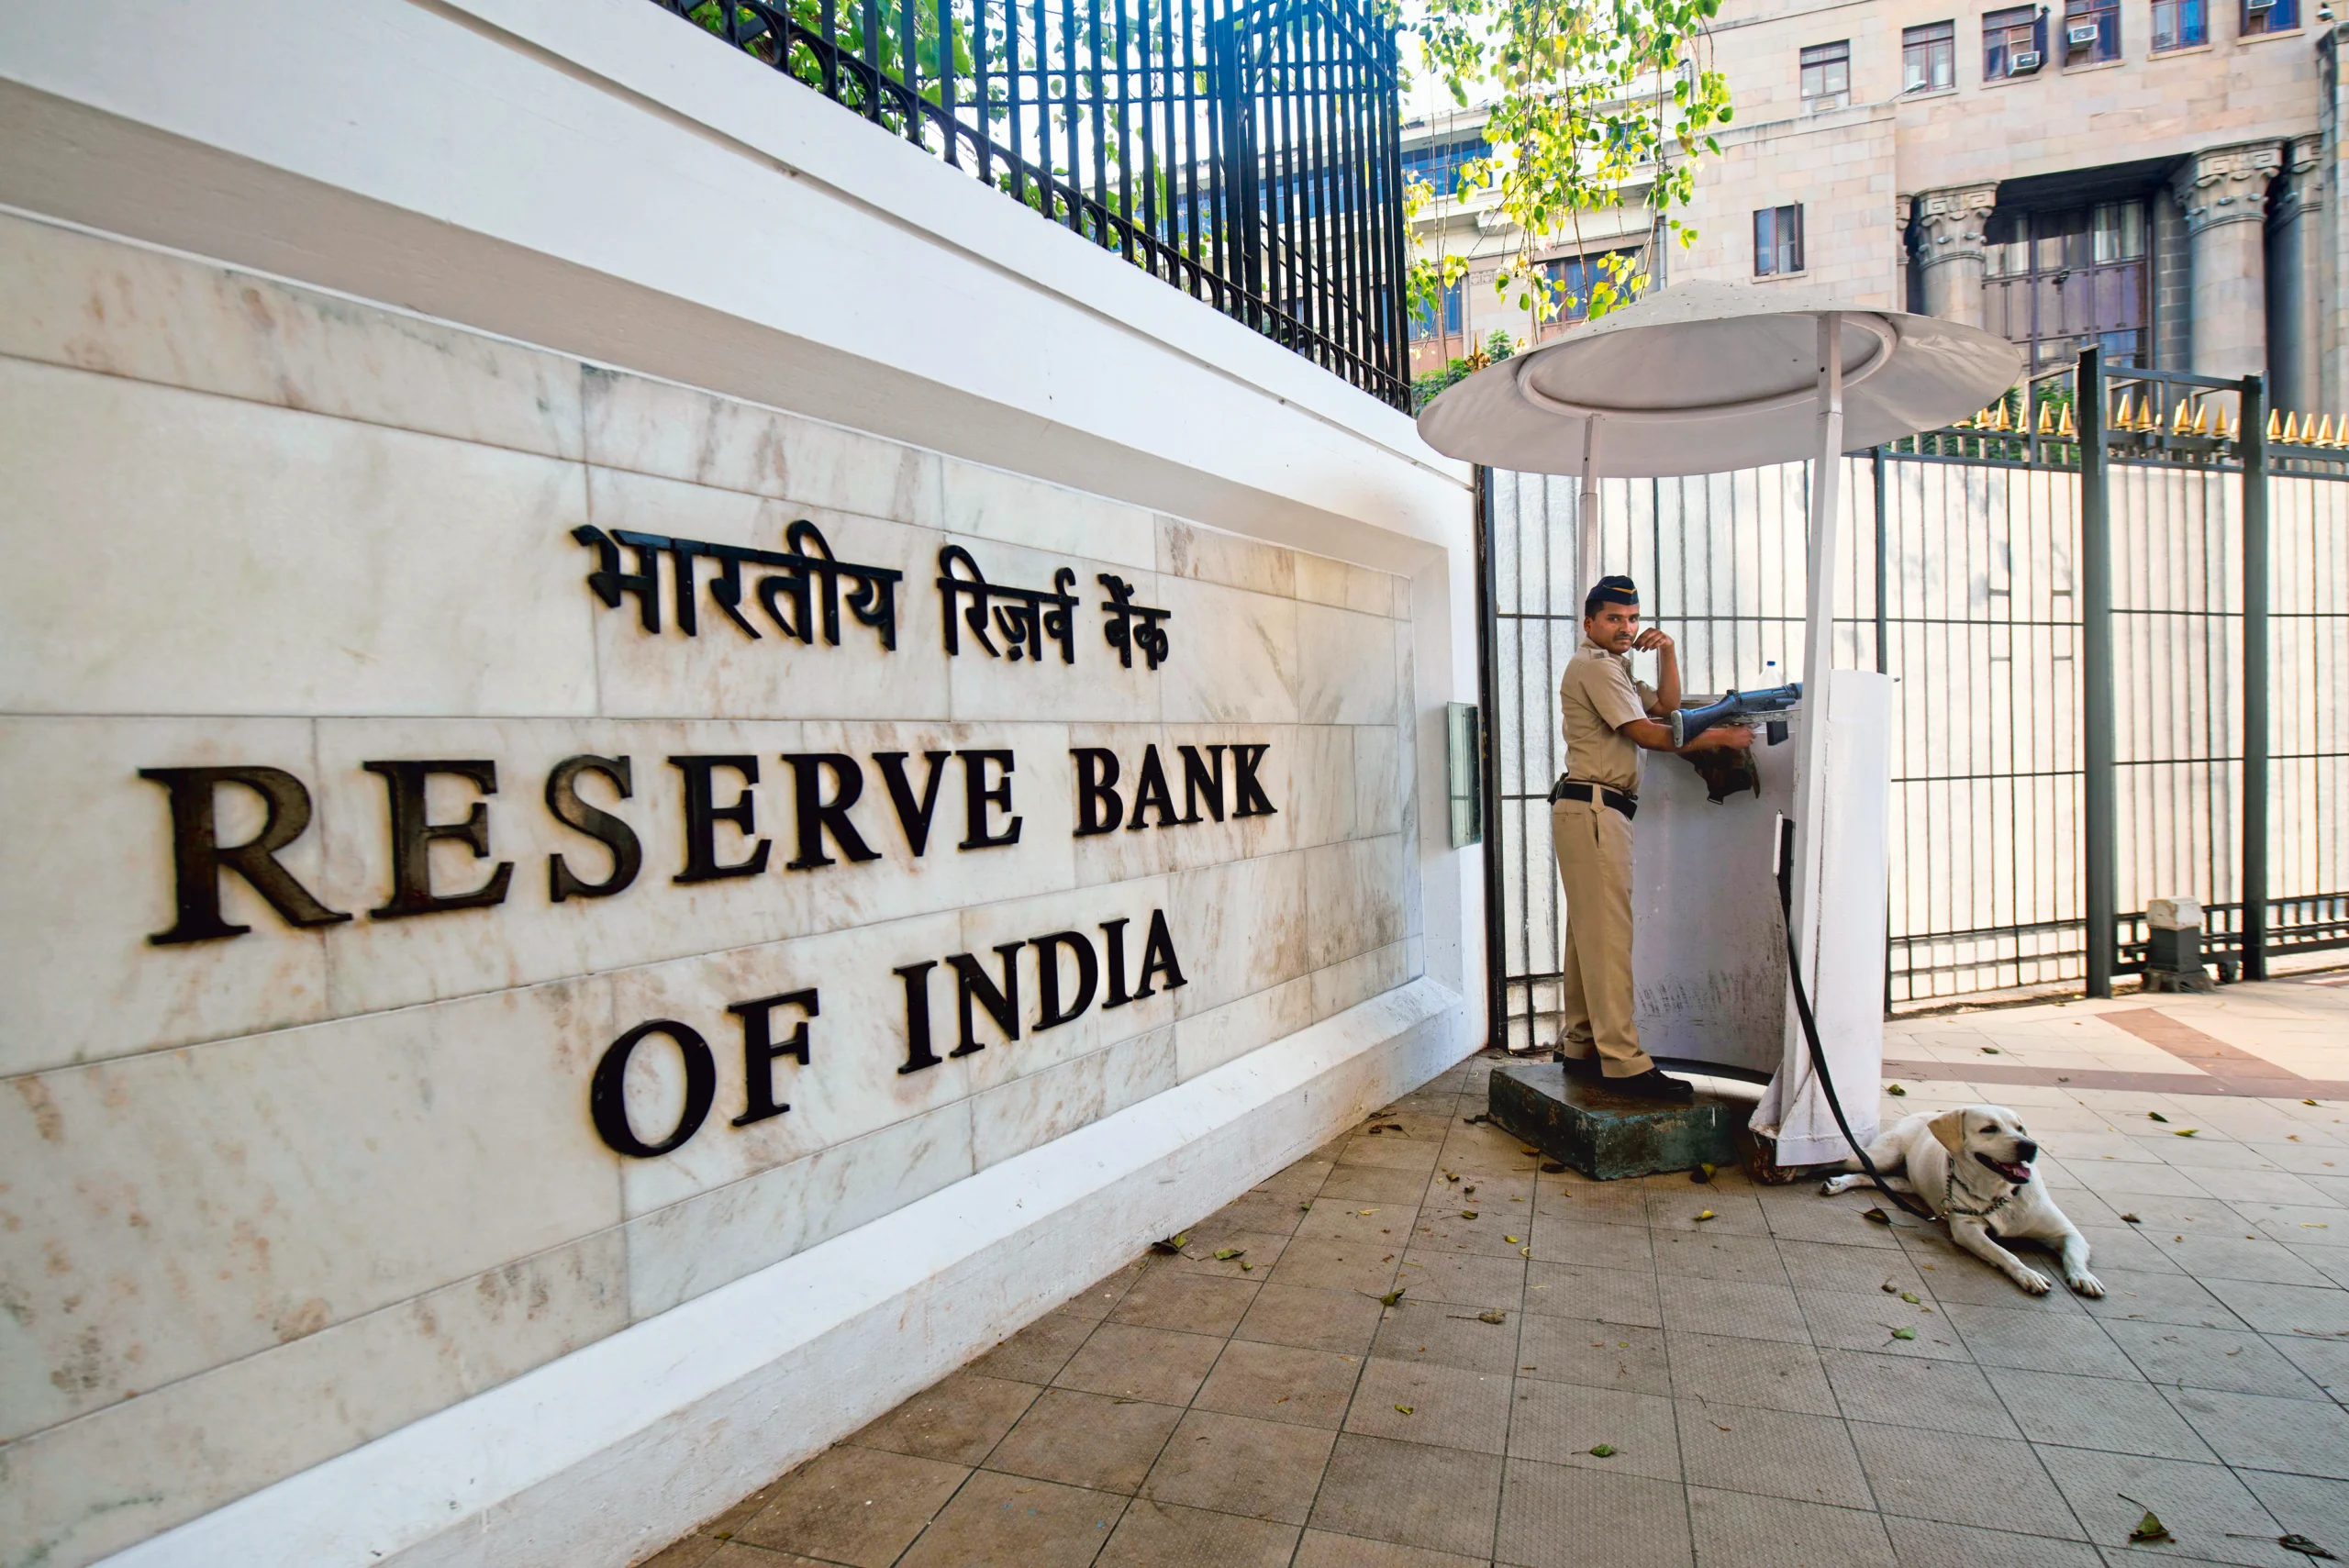
The Reserve Bank of India’s (RBI) decision to tighten daily Cash Reserve Ratio (CRR) maintenance requirements could withdraw between ₹400 billion and ₹800 billion from the banking system, while marginally increasing funding costs for banks, according to a report by brokerage firm Jefferies.
The revised norms are expected to have a limited impact on banks’ net interest margins (NIMs), although the additional liquidity constraints could influence lending conditions, borrowing costs and funding for non-banking financial companies (NBFCs).
According to the report, the RBI’s move aligns with the Monetary Policy Committee’s shift towards a stance of “calibrated tightening”. The decision changes how consistently banks must maintain their prescribed cash reserves with the central bank, without altering the statutory CRR rate.
RBI Raises Daily CRR Maintenance Requirement to 99%
Under the revised rules, banks must maintain 99% of their prescribed CRR daily, compared with the earlier requirement of 90%. The statutory CRR remains unchanged at 3% of Net Demand and Time Liabilities (NDTL).
The higher daily maintenance requirement could encourage banks to hold more funds with the RBI rather than deploy them for lending and other business activities. This could marginally reduce the liquidity available across the banking system.
Jefferies estimates that if banks increase their reserve balances by 5% to 10%, the move could withdraw ₹400 billion to ₹800 billion in liquidity and raise their cost of funds by 1–2 basis points.
The brokerage noted that banks currently maintain a buffer above the minimum daily CRR requirement. However, the revised rules could require them to set aside additional funds, potentially increasing their funding costs.
Limited Impact Expected on Banks’ Net Interest Margins
Despite the potential liquidity withdrawal, Jefferies expects the impact on banks’ profitability to remain limited. The estimated increase in funding costs is relatively small and is unlikely, by itself, to cause a substantial deterioration in net interest margins.
NIM measures the difference between the interest a bank earns on loans and investments and the interest it pays on deposits and other funding, relative to its interest-earning assets.
Jefferies said the additional funding burden could lead to a small dilution in NIMs, adding that banks may be able to pass the marginal increase in costs on to borrowers.
However, the extent of such a pass-through will depend on lending conditions, competition among banks and their ability to adjust loan pricing. If banks absorb the additional costs instead, their margins could face some pressure.
NBFCs and Corporate Borrowers Could Also Face Higher Costs
The effects of the revised CRR norms could extend beyond banks if lenders respond to higher funding costs by adjusting lending rates.
Non-banking financial companies, which depend on banks and other funding channels to finance their operations, could face higher borrowing costs if banks pass on the increase. Corporates seeking loans or working capital finance could also be affected.
The overall impact will depend on individual banks’ funding strategies, loan pricing decisions and borrowers’ ability to absorb any increase in interest rates.
If borrowing costs rise, some businesses may reconsider their financing plans, while NBFCs could face pressure on funding expenses. However, the extent of these effects remains uncertain and will depend on how banks respond to the revised requirements.
Jefferies Prefers Banks Over NBFCs in a Rising-Rate Environment
Jefferies said it prefers banks over NBFCs in a rising interest rate environment, reflecting differences in their funding structures and their ability to manage higher borrowing costs.
Banks generally have diversified funding sources, including customer deposits, while NBFCs may rely more heavily on bank borrowings, market instruments and other funding arrangements. The relative impact of rising rates can therefore differ across institutions.
The brokerage’s preference highlights the importance of funding costs and balance-sheet management when assessing financial-sector companies during periods of tighter liquidity or rising interest rates.
What the Revised CRR Norm Means for the Banking Sector
The RBI’s tighter daily CRR maintenance requirement could modestly reduce system liquidity and increase banks’ funding costs, even though the statutory CRR remains unchanged at 3%.
Jefferies expects the immediate impact on banks’ margins to be limited, with the possibility that lenders could pass some additional costs on to borrowers. The resulting effects on credit demand, NBFC funding and corporate borrowing will depend on banks’ pricing decisions and broader market conditions.
For investors, the key factors to monitor will be changes in bank funding costs, NIM performance, lending rates and liquidity conditions. While the revised norms may create some pressure on margins, the brokerage’s assessment suggests that the direct profitability impact is likely to remain modest.